The Yen's Volatility: A Coordinated Intervention and its Implications for Investors
ByMichele Ferrero
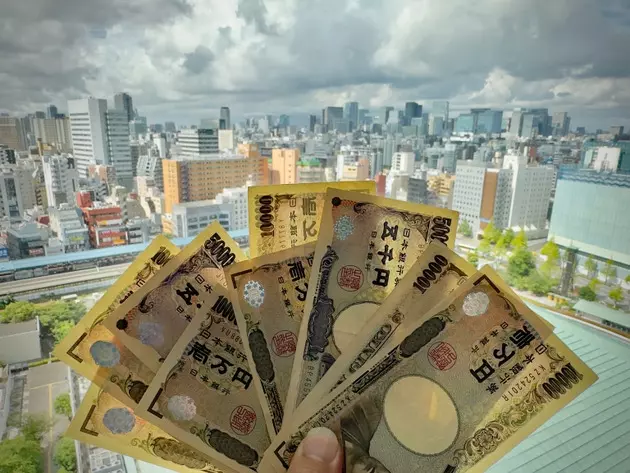
This report delves into the recent coordinated currency market intervention by Japan and the United States, examining its immediate effects and long-term implications for global investors, particularly those engaged with Japanese equities.
Navigating Currency Crosscurrents: Understanding the Yen's New Reality
The Unprecedented Collaboration in Currency Markets
Japan and the United States recently undertook a synchronized intervention in the foreign exchange markets, triggering an extraordinary 5-standard deviation shift in the dollar-yen exchange rate. This move was not merely a unilateral action by Japan, which has a history of currency intervention, but a meticulously coordinated effort with the US Treasury Department. A key distinguishing factor of this particular intervention was the strategic deployment of volatility as a tool to discourage speculative trading activities, marking a significant departure from conventional approaches.
The Yen's Valuation Conundrum: Cheap Yet Vulnerable
From a fundamental perspective, the Japanese Yen appears considerably undervalued. However, this inherent attractiveness is overshadowed by a complex interplay of macroeconomic factors. Japan's ongoing expansionary fiscal policy, coupled with a monetary policy that diverges significantly from global trends, creates an environment typically conducive to a weaker currency. This creates a challenging landscape where intrinsic value clashes with policy-driven depreciation pressures.
Investor Considerations in Japanese Equities: The Hedging Imperative
For investors holding Japanese equities, the fluctuating yen introduces a critical dimension: currency exposure. Whether their investments are currency-hedged or unhedged, their positions implicitly reflect a view on the yen's future trajectory. It is crucial for these investors to consciously and deliberately formulate this currency view rather than letting it be an unintended consequence of their equity holdings. The performance data underscores this point: the FTSE Japan 100% Hedged index, when measured in USD, has consistently outperformed its unhedged counterpart over one, three, and five-year periods, highlighting the tangible benefits of strategic currency management.
About the author
Michele Ferrero
Noted for building the Ferrero Rocher empire, representing entrepreneurial finance success.