Wendy's Struggles in Q2: Sales Decline and Market Share Erosion
ByDavid Rubenstein
This analysis delves into Wendy's recent financial performance, highlighting the company's struggles in a highly competitive market and the potential implications for investors.
Wendy's: Navigating a Challenging Market with Declining Performance
Challenging Consumer Spending Environment
Despite a robust S&P 500 rally, the Q2 earnings season reveals that many businesses, particularly those dependent on robust consumer spending, are on unstable ground. This trend is especially evident in the quick-service restaurant sector.
Wendy's Q2 Performance: A Closer Look
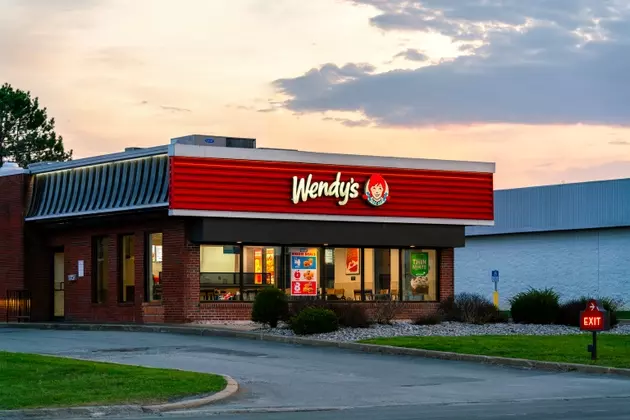
Wendy's (WEN) reported a significant decline in its Q2 performance, with same-restaurant sales in the U.S. falling by 3.6%. This drop was accompanied by a 12.5% decrease in customer traffic, leading to a sharp deterioration in profit margins. These figures indicate a weakening competitive position against its rivals.
The Impact of Substantial Debt on Operational Flexibility
The company carries a considerable debt load of $2.76 billion, severely limiting its financial maneuverability. Consequently, Wendy's is largely depending on the expansion of new restaurant locations to achieve even modest revenue growth, rather than organic sales improvements.
Uncertainty and Risk: Guidance Withdrawal and Inconsistent Promotions
Adding to the concerns, Wendy's has retracted its full-year financial guidance. This, coupled with an inconsistent approach to promotional activities, signals increased business risks. In such a fiercely competitive environment, these factors make the company a less attractive investment option.
Recommendation: Exercise Caution
Given the persistent decline in sales, erosion of market share, substantial debt burden, and the withdrawal of future guidance, I advise investors to avoid Wendy's stock at this time. The current market conditions and internal challenges present a difficult path for the company.
About the author
David Rubenstein
Co-founder of The Carlyle Group, author, and interviewer discussing economic history and leadership.