Suze Orman's Retirement Advice: Transforming a 'D-Minus' into an 'A' for Early Retirees
ByScott Pape
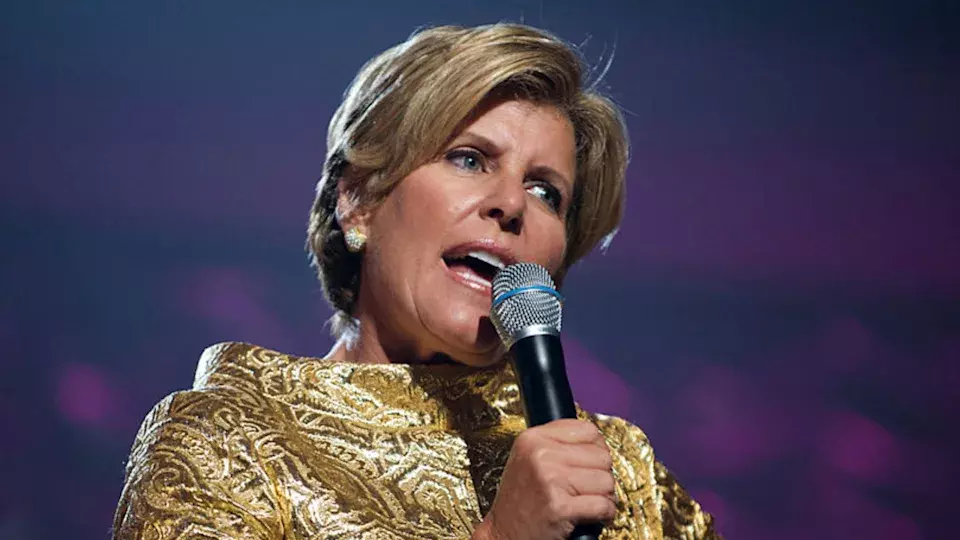
This article delves into the critical considerations for retirement planning, particularly for those envisioning an early exit from the workforce. It highlights a real-life scenario where financial guru Suze Orman provides transformative advice to a woman seeking to retire at 55, demonstrating how strategic adjustments can drastically improve one's financial outlook for the golden years.
Unlock a Million More: How a Few Extra Years Can Redefine Your Retirement Future
Megan's Aspiration for Early Retirement: A Personal Motivation
Megan, a 48-year-old single parent, harbors a strong desire to retire by age 55. Her motivation stems from a deeply personal experience: her father's passing at 66, just months before his planned retirement. This event instilled in her a determination to enjoy her post-working life sooner rather than later.
Initial Retirement Readiness Assessment: A Harsh Reality Check
Despite Megan's self-assessment of a B-minus for her retirement preparedness, financial expert Suze Orman's analysis revealed a starker reality. Orman, after reviewing Megan's financial standing, assigned a 'D-minus' grade to her goal of retiring at 55, indicating significant gaps in her current plan.
The Compounding Power of Time: Why Every Year Counts
Orman emphasized the profound impact of compound interest and the benefits of not prematurely halting one's career. Working longer allows for continued contributions to retirement accounts, maximizing the exponential growth of investments over time. This extended period also permits 'catch-up' contributions for those over 50, further accelerating savings.
Navigating the Financial Landscape of Early Retirement: Hidden Costs and Missed Opportunities
Retiring before the traditional age of 65 carries several financial implications. These include the necessity of private health insurance until Medicare eligibility, potential early-withdrawal penalties from retirement accounts, and the forfeiture of peak earning years. Such factors underscore the importance of a meticulously planned financial strategy.
Megan's Financial Snapshot: A Foundation for Growth
Megan's current financial portfolio includes substantial retirement savings, diverse investments, and a solid emergency fund. Her home equity and minimal car debt further strengthen her position. However, to achieve a robust early retirement, Orman’s insights reveal that her existing assets, while considerable, are insufficient for a comfortable multi-decade retirement without further accumulation.
Orman's Transformative Counsel: Extending Work Life for Enhanced Security
To turn Megan's 'D-minus' into an 'A', Orman suggested a seemingly small but impactful adjustment: working until age 62. This extension, just seven additional years, would significantly boost her retirement funds, potentially adding an extra million dollars and substantially increasing her monthly retirement income, ensuring a more secure and worry-free future.
Strategic Retirement Planning: Maximizing Benefits and Avoiding Pitfalls
Deciding the optimal retirement age involves balancing personal aspirations with financial realities. Understanding the rules surrounding 401(k) withdrawals, Social Security benefits, and capital gains taxes is crucial. Financial advisors can play a vital role in crafting a personalized plan that accounts for individual circumstances and long-term financial health.
Embracing a Longer Horizon: The Ultimate Retirement Reward
Ultimately, Orman's advice to Megan highlights that a few more years in the workforce can translate into a dramatically more comfortable and enjoyable retirement. By strategically delaying retirement, individuals can build a stronger financial foundation, allowing them to truly "hope and wish that you live a long, long life" with the means to support it.
About the author
Scott Pape
"The Barefoot Investor," an author whose plain-talking financial advice is immensely popular in Australia.