Global PC Shipments Plummet Over 20% Amidst Economic Headwinds
ByRoberta Williams
Recent data from IDC Research reveals a substantial decrease in global personal computer deliveries during the third quarter of 2026. Shipments plunged by a remarkable 20.1% compared to the same period in the previous year, with unit figures dropping from 78.5 million to 62.7 million. This significant contraction in the market underscores a challenging environment for PC manufacturers and consumers alike.
The primary catalyst for this downturn, as identified by the IDC, is a critical shortage in memory and disruptions across the supply chain, largely fueled by the surging demand for AI servers. This situation has led to elevated component costs, which in turn have translated into higher retail prices for PCs. These increased costs, coupled with a broader economic slowdown, have dampened consumer enthusiasm and purchasing capabilities. Vendors had front-loaded their inventory acquisitions earlier in the year to preempt anticipated price escalations, effectively drawing demand from the latter half of the year. This strategy artificially boosted early-year shipment numbers but ultimately left the third quarter with a significant deficit in demand, disrupting typical seasonal patterns where the third quarter usually surpasses the second.
Industry projections suggest that the market conditions are unlikely to improve in the immediate future. Concerns among channel partners about accumulating excess inventory in a market characterized by high prices and weak demand could potentially lead to some promotional activities. However, experts caution that any price reductions will still keep costs considerably above the levels observed a year prior. The overarching economic climate poses a greater risk, with a deteriorating global outlook potentially further suppressing demand and casting a shadow over the remainder of 2026 and into 2027.
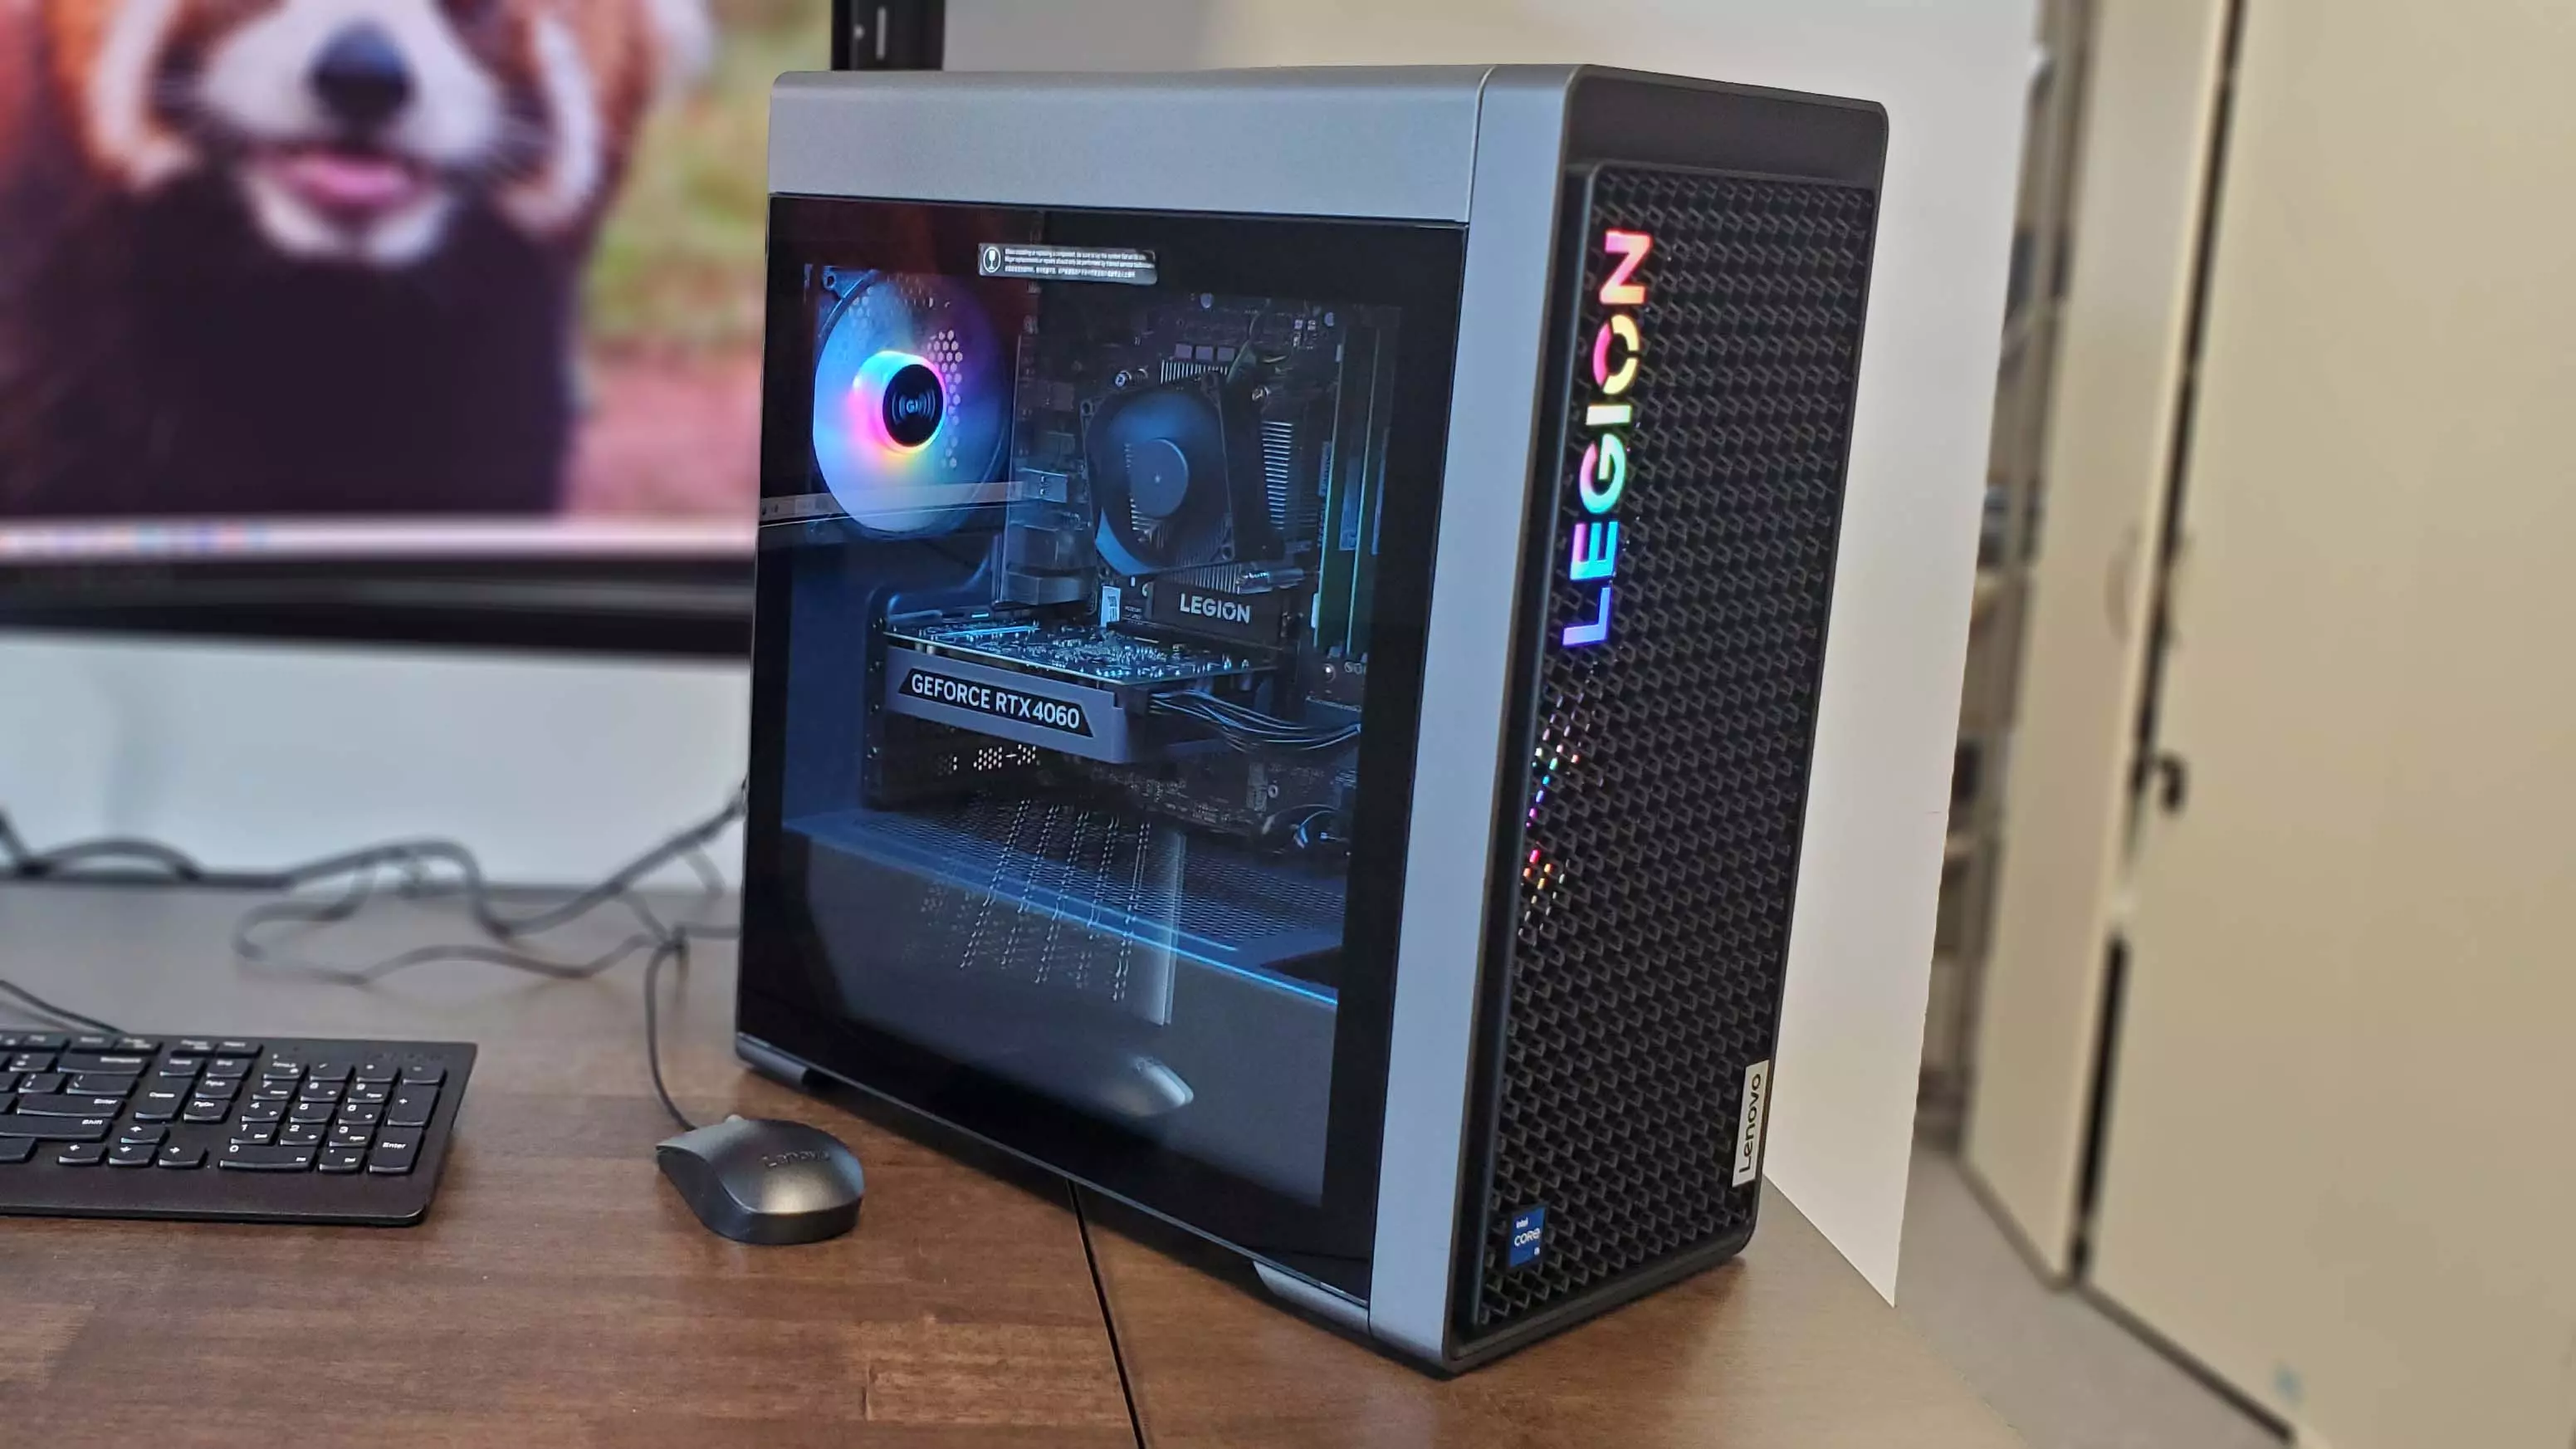
The impact of this market shift has not been uniformly distributed among manufacturers. Leading brands such as Lenovo, HP, and Dell experienced more pronounced declines than the overall market average, collectively losing 4.2 market share points. HP was particularly affected, seeing its share fall from 19.1% to 16.5%. Despite these setbacks, Lenovo maintained its position as the largest PC shipper globally, followed by HP in second and Dell in third. Apple also registered an 11.3% dip in growth, while Asus saw its figures decline by 8.6%. These figures highlight the widespread challenges faced by major players in the personal computing industry.
The consensus among market observers, including key industry figures, is that the memory crisis and its ripple effects will continue to influence PC pricing for an extended period. Despite the possibility of some promotional efforts, prices are expected to remain elevated compared to the previous year. The broader economic landscape continues to darken, indicating that conditions for the PC market may worsen before any significant recovery takes hold. This prolonged period of high prices and reduced accessibility could reshape consumer buying habits and industry strategies for the foreseeable future.
About the author
Roberta Williams
Pioneer of graphic adventure games, co-founder of Sierra On-Line, and creator of "King's Quest."