Figma vs. IBM: Analyzing Revenue Trajectories for Design Innovator and Tech Veteran
ByMr. Money Mustache
This article provides an in-depth comparison of the revenue performance between Figma, a modern software design company, and IBM, a long-standing technology enterprise specializing in AI. It delves into their respective financial trajectories, offering valuable perspectives for investors analyzing market presence and growth potential.
Unpacking the Financial Journeys of Tech Innovators and Giants
Figma's Consistent Ascent in Revenue Generation
Figma, trading under the ticker symbol NYSE:FIG, generates its income through subscriptions to its cutting-edge, browser-based collaborative design and prototyping software. The company recently unveiled new animation tools at its annual conference in June 2026. Despite a reported net income margin of approximately -43% for the quarter ending March 31, 2026, Figma continues to demonstrate remarkable growth in its core business.
IBM's Revenue Dynamics Amidst Market Shifts
International Business Machines (NYSE:IBM) offers an extensive portfolio of technology solutions, expert consulting services, and hybrid cloud infrastructure to its diverse global client base. The company announced a preliminary earnings shortfall on July 14, 2026, even as it posted a 15% EBIT margin for the quarter concluding on June 30, 2026. IBM's journey through market fluctuations highlights its strategic adjustments in a rapidly evolving tech landscape.
The Significance of Revenue for Individual Investors
Revenue figures are a fundamental metric for investors, representing the total financial inflow before any expenditures. Monitoring this indicator is essential for grasping a company's overall operational size and its trajectory of top-line expansion. It offers a clear picture of a business's health and market momentum.
Comparative Quarterly Revenue Overview of Figma and IBM
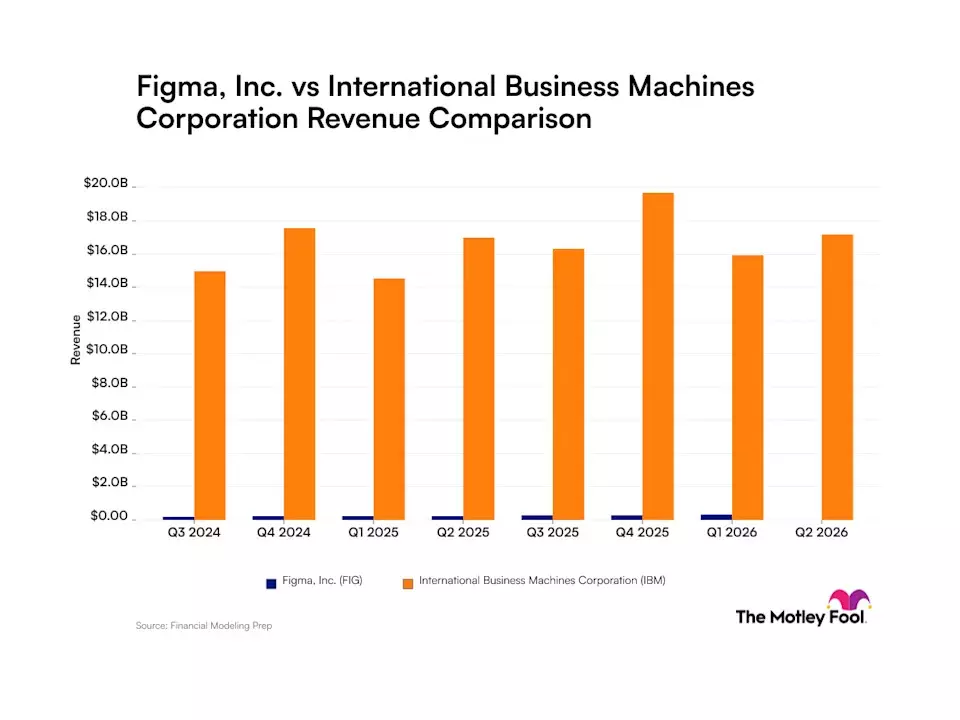
According to company filings updated as of July 24, 2026, the quarterly revenue data for both Figma and International Business Machines reveals distinct patterns. This data provides a foundational basis for understanding their individual financial narratives and comparative market standing.
An Analytical Perspective: The Foolish Take
While the venerable IBM boasts a revenue scale far exceeding that of the newer Figma, a company with over a century of existence, this disparity is expected. IBM has undergone significant transformations, now concentrating on the burgeoning artificial intelligence sector. It provides crucial software and cloud infrastructure for AI adoption, complemented by a vast network of consultants. In contrast, Figma's robust sales trends underscore the success of its design-centric business model. Despite concerns about AI's potential impact on design tools, Figma's thriving sales indicate continued customer adoption and strong market performance.
Market Reactions to IBM's Performance and the AI Boom
IBM's fluctuating sales reflect the inherent volatility in selling hardware and consulting services. The initial success of its AI-integrated zSystems mainframes was followed by a 42% year-over-year decline in Z sales in the second quarter of 2026. This, coupled with falling short of Wall Street's Q2 revenue forecasts amidst the AI surge, led to investor concern, driving IBM shares to a 52-week low of $199.19 on July 23.
Figma's Impressive Sales Trajectory and Market Perception
Figma's revenue trend is a testament to its business efficacy. The company reported first-quarter sales of $333.4 million, marking an impressive 46% year-over-year growth and continuing its streak of quarterly increases. Projections for the second quarter anticipate revenue between $348 million and $350 million. Despite its stock falling to a 52-week low of $16.60 in April due to AI-related concerns, Figma's sales figures clearly show its business is flourishing, successfully navigating the evolving technological landscape.
About the author
Mr. Money Mustache
Pseudonym for Pete Adeney, a blogger who popularized extreme early retirement through frugality and investing.